Shift in the AI Competitive Landscape
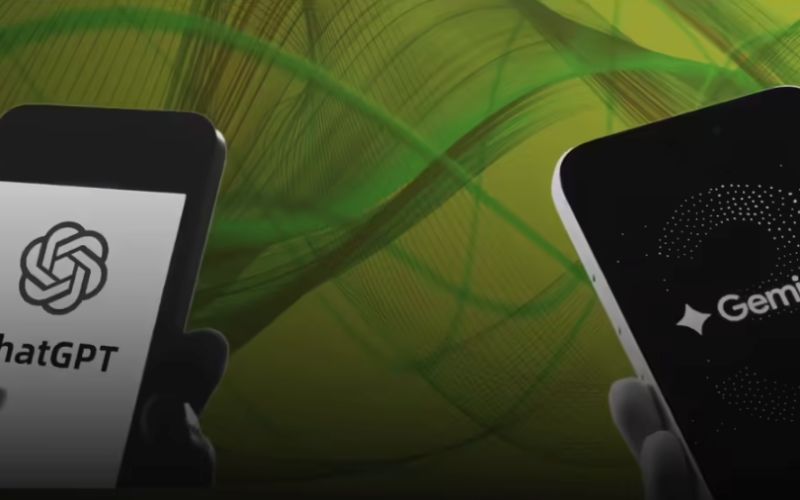
- The Financial Times reports that OpenAI — which long held a dominant lead thanks to its early‑mover advantage with ChatGPT — is now facing “the biggest pressure since ChatGPT launched,” as rivals accelerate their advances.
- According to FT, OpenAI’s valuation has soared to roughly $500 billion. Yet, the company is now confronting rapidly rising data‑center costs, intensifying technical challenges to stay at the frontier, and fierce competition for AI talent.
📈 Why Google & Anthropic Are Catching Up
- Google recently launched its new large‑language model, Gemini 3, which — per multiple industry sources — reportedly outperforms OpenAI’s GPT‑5 on key benchmarks.
- Google’s “full‑stack” setup — combining proprietary custom chips (e.g., Tensor Processing Units for AI training), massive infrastructure, and an enormous existing user base — gives it a significant advantage in scaling and performance.
- Meanwhile, Anthropic — another major competitor — continues to push forward with its own model development and enterprise‑oriented AI offerings, further increasing pressure on OpenAI.
📝 Consequences Within OpenAI: “Code Red.”
- Facing this pressure, OpenAI CEO Sam Altman reportedly issued an internal “code red.” The company is refocusing its efforts on improving core product ChatGPT, prioritizing speed, reliability, and personalization, while delaying secondary projects such as ad tools, shopping/health agents, and other planned services.
- This signals a reckoning: what was once considered a comfortable lead may no longer hold in a landscape where multiple players now deliver top‑tier models.
📊 What This Means for the Broader Industry
- The AI race may be shifting from a near‑monopoly (single dominant player) to a multi‑polar competition, with several “top‑tier” labs and companies — each with unique strengths (inference chips, cloud infrastructure, enterprise integration, scale, etc.).
- Investment, infrastructure, and scale are increasingly important: the advantage now comes not just from having a powerful model, but from being able to support it with custom hardware, data centers, and wide integration.
• • For users and businesses, the proliferation of capable models from multiple providers may lead to faster innovation, more choice, and possibly downward pressure on licensing/service costs — but it also raises questions about fragmentation, model divergence, and interoperability.
The above content is compiled by ModeZone, a fashion and entertainment magazine.